Cassie Nestor
Research Associate
Get to Know Cassie


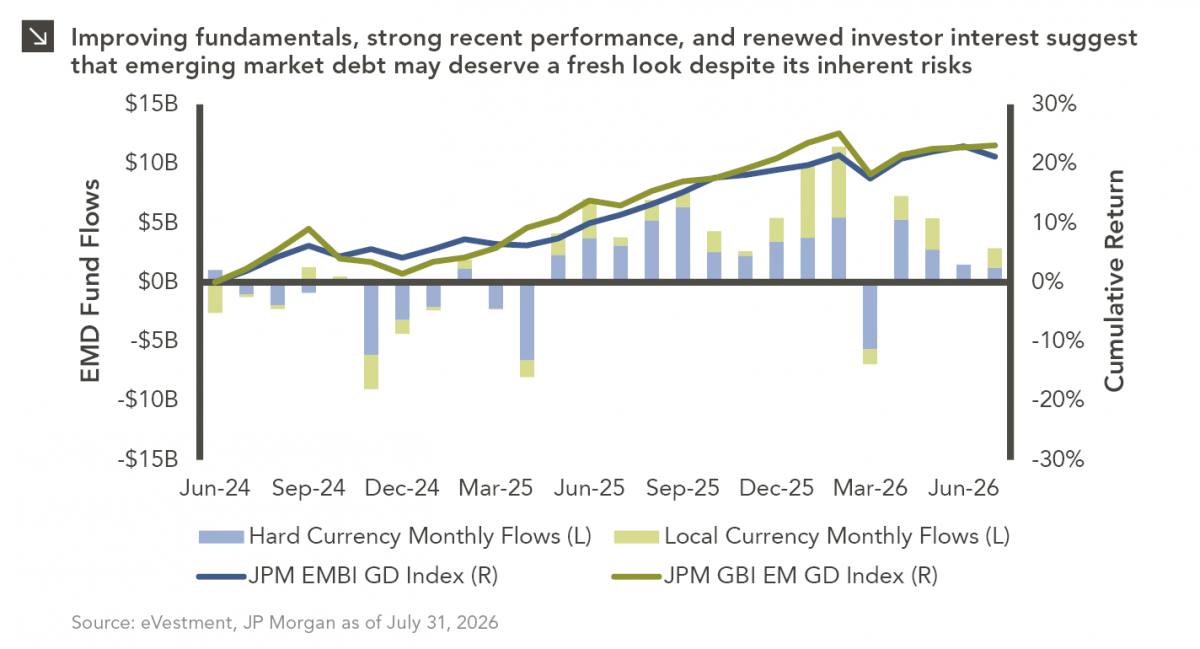
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income sectors narrowing the traditional yield advantage of the space. While many investors have overlooked or even exited EMD funds as a result of these challenges, recent developments have driven some investors back to the asset class. For instance, many emerging market countries have implemented meaningful structural reforms, particularly following the economic challenges associated with the COVID-19 pandemic. These countries have made progress in reducing inflation, managing government spending, and strengthening monetary and fiscal policy frameworks. Additionally, the continued development of domestic investor bases for local-currency debt has improved countries’ ability to withstand external shocks and reduced their reliance on foreign capital flows. Sovereign credit fundamentals have also improved, with credit upgrades gradually outpacing downgrades across the emerging market universe.
As some of the traditional risks associated with emerging market bond investing have moderated, performance has improved. To that point, EMD was the top-performing major fixed income asset class in 2025, and this momentum has continued so far this year. As of July 31, hard- and local-currency EMD indices have both returned roughly 1.8% on a year-to-date basis, respectively, outpacing high yield and core bonds over the same timeframe. Additionally, since the end of 2024, these indices have returned 10.1% and 13.1%, respectively. For context, the key difference between these indices is that local-currency debt exposes investors to both interest rate and currency movements, whereas hard-currency debt largely eliminates direct exposure to the issuing country’s currency.
Improving fundamentals have also supported renewed capital flows into the asset class. According to EPFR, cumulative EMD fund inflows for 2026 surpassed $31 billion as of the end of July. It is important to note that the composition of those flows is evolving. Historically, hard-currency debt has dominated investor allocations, but more than 50% of EMD fund flows have been directed toward local-currency strategies in 2026. Several factors could be contributing to this dynamic, including a weaker U.S. dollar, attractive local interest rates, improving macroeconomic fundamentals, and growing confidence in the stability of emerging market currencies.
All of this being said, EMD remains a complex asset class that poses risks related to interest rates, currencies, sovereign credit quality, and capital flows. Foreign investment flows can also introduce volatility during periods of market stress and risk-off environments. Nevertheless, the recent outperformance of EMD indices has clearly not gone unnoticed by investors, and the improving fundamentals and diversification benefits offered by the asset class suggest that it may deserve a second chance.
Print PDF
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.12.2026
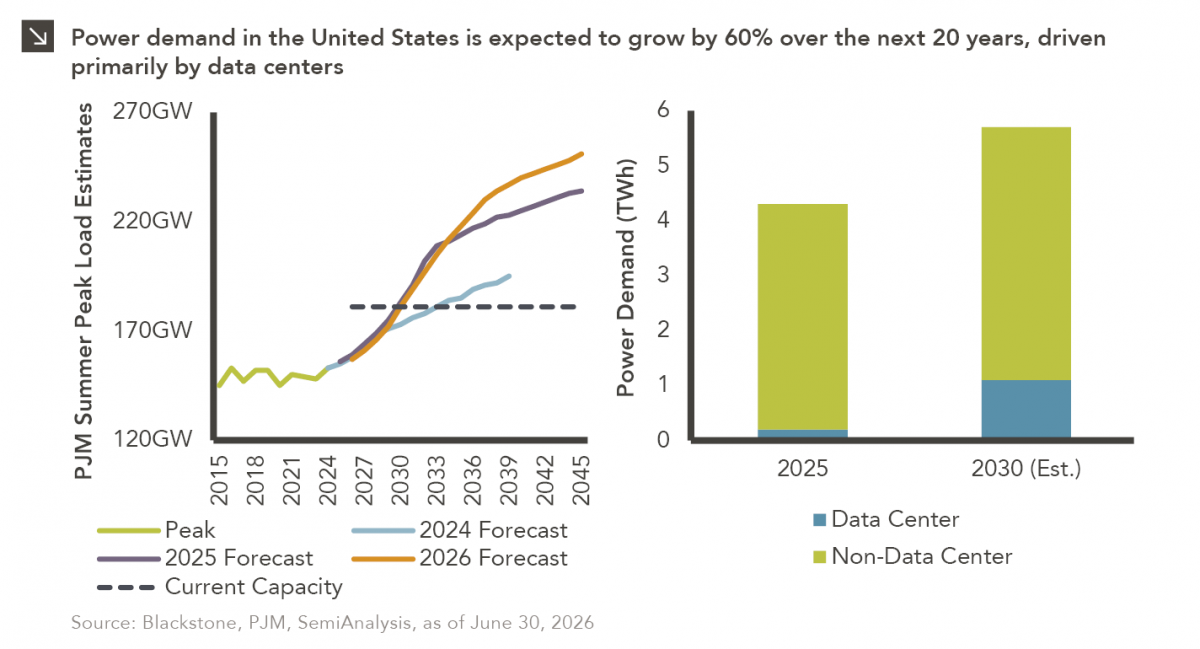
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
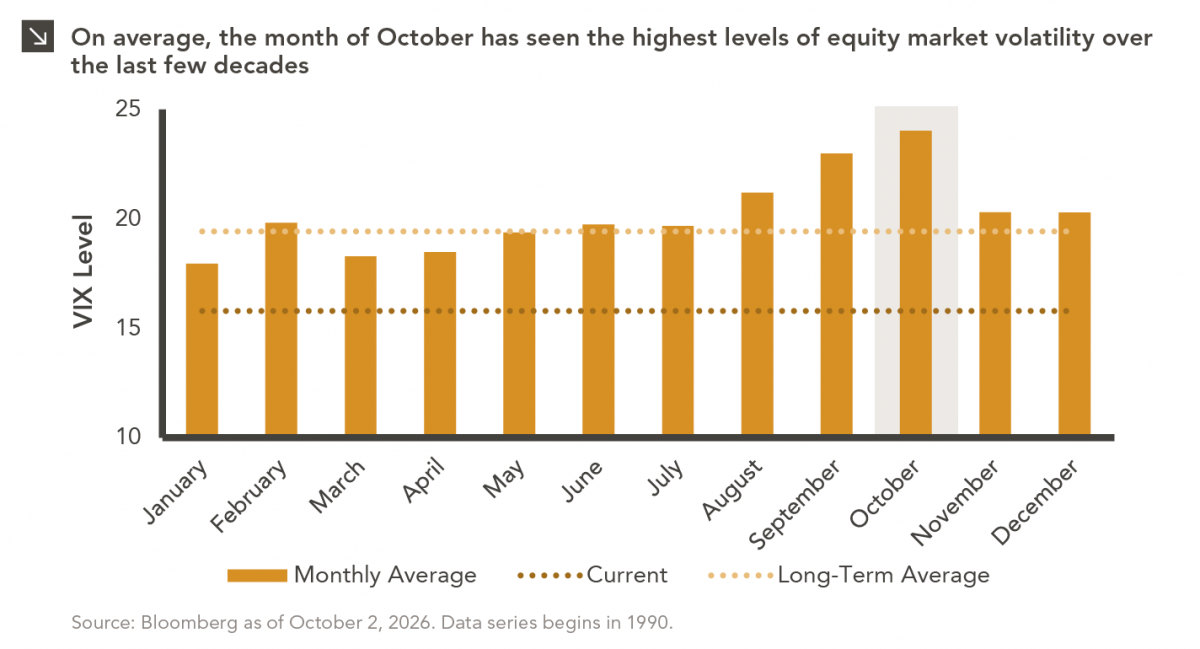
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >