Frank Valle, CFA, CAIA
Associate Director of Fixed Income


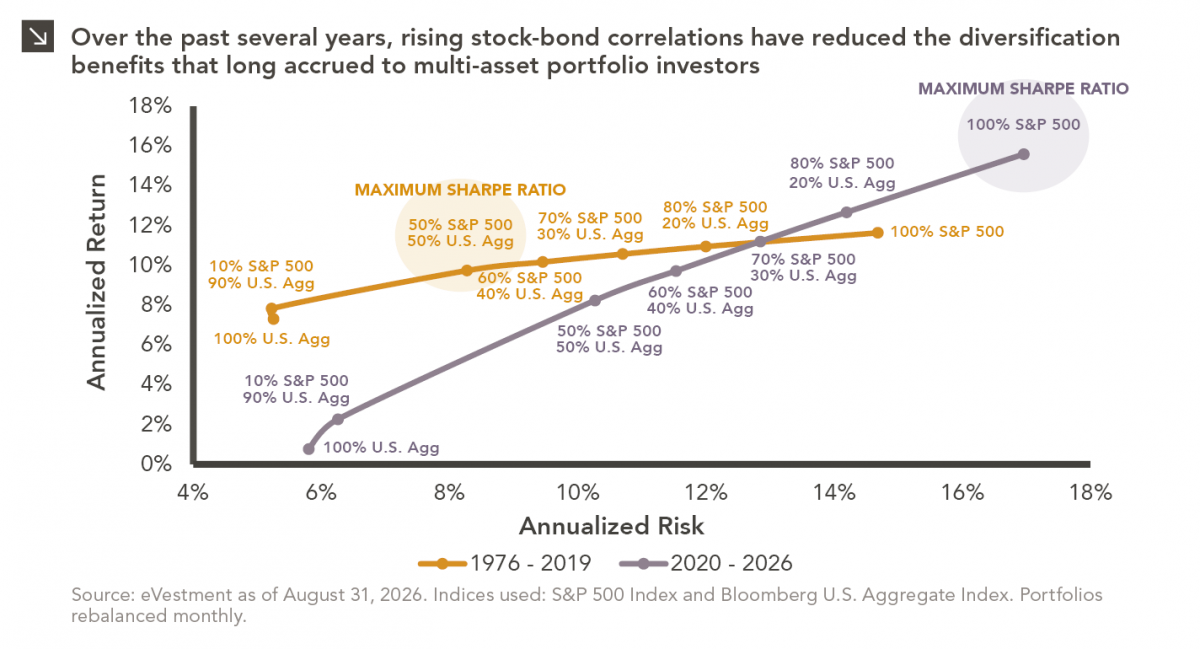
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of the list for many employees. Each week, the company generously provides catered cuisine from one of Chicago’s many fine dining establishments, and team members gather in the cafeteria to enjoy great conversation, build connections across the firm, and eat a tasty meal free of charge! Of course, since Marquette is ultimately footing the bill, these lunches are technically not “free.” In fact, Nobel Prize-winning economist Harry Markowitz famously stated that “diversification is the only free lunch in investing,” meaning that risk-adjusted returns can be improved simply by combining different assets within a portfolio. For more than four decades, this maxim held true, as an investor could add equity exposure to a fixed income portfolio and increase overall returns while also reducing risk. Specifically, from 1976 through the end of 2019, the Bloomberg U.S. Aggregate Bond Index notched annualized return and standard deviation figures of 7.3% and 5.3%, respectively. Given the lack of correlation between stocks and bonds during that period, however, an investor could have created a portfolio with a 90% allocation to the Bloomberg U.S. Aggregate Bond Index and a 10% allocation to the S&P 500 Index to increase overall returns while decreasing risk. This diversification benefit (i.e., free lunch) can be observed on the left-hand side of the chart above.
Another Nobel laureate, Milton Friedman, famously argued that “there is no such thing as a free lunch,” emphasizing that every benefit comes with an associated opportunity cost. The last several years have certainly supported this notion, as the slope of the efficient frontier of stock-bond portfolio combinations has increased significantly since the start of 2020, and investors across the spectrum of combinations have been required to accept greater risk to achieve higher returns. Remarkably, the 100% S&P 500 Index portfolio exhibited the highest Sharpe ratio (0.69) of any of the combinations on the 2020–2026 efficient frontier, meaning that any amount of fixed income exposure led to lower risk-adjusted returns for investors over this period. This is in stark contrast to the 1976–2019 period, during which the 100% S&P 500 Index had the lowest Sharpe ratio of any possible combination on the efficient frontier (0.51), with the highest being a combination closer to 50% S&P 500 Index and 50% Bloomberg U.S. Aggregate Bond Index (0.65).
The primary driver of the dynamics detailed above has been the breakdown in the traditional relationship between stocks and bonds. Historically, bonds exhibited low or even negative correlation with equities, providing meaningful diversification benefits within multi-asset portfolios. For instance, during periods of economic expansion in previous decades, stronger growth and rising interest rates often weighed on bond prices while supporting corporate earnings and stock valuations. Conversely, during periods of economic stress, declining interest rates generally boosted bond prices while causing equities to come under pressure. Indeed, from 1976 through 2019, the Bloomberg U.S. Aggregate Bond Index exhibited a correlation of 0.20 with the S&P 500 Index. This relationship, however, has changed materially since the start of 2020. That year, the Federal Reserve responded to the economic shock caused by the COVID-19 pandemic with aggressive monetary easing, driving interest rates sharply lower and supporting strong returns across both fixed income and equity markets. The Bloomberg U.S. Aggregate Bond and S&P 500 indices returned 7.5% and 18.4%, respectively, in 2020. In 2022, circumstances shifted sharply, as high inflation, tighter financial conditions, and concerns around corporate profitability proved challenging for most asset classes, and the Bloomberg U.S. Aggregate Bond and S&P 500 indices returned -13.0% and -18.1%, respectively. One notable factor contributing to the higher correlation between stocks and bonds in recent periods has been the increasing concentration of growth-oriented companies within equity indices. Because these businesses derive a significant portion of their value from cash flows expected far in the future, their valuations are particularly sensitive to interest rate fluctuations. As a result, rates have played a more prominent role in determining both fixed income and equity returns over the last few years, increasing the likelihood that the two asset classes move in the same direction. To that point, the correlation between the Bloomberg U.S. Aggregate Bond Index and the S&P 500 Index has been 0.51 since the start of 2020.
While the benefits of a traditional stock-bond portfolio may now be less pronounced than they have been historically, diversification remains a valuable portfolio construction tool because equities and fixed income are still not perfectly correlated. Even if the two asset classes move in the same direction over the coming quarters, the higher bond yields offered today provide a meaningful source of income and return that was largely absent during the low-rate environment of the early 2020s. Additionally, as inflation continues to moderate and monetary policy normalizes, the historical relationship between stocks and bonds is likely to reassert itself, which may restore some of the diversification benefits investors have come to expect from multi-asset portfolios. Although the diversification benefits of a traditional stock-bond portfolio have diminished in recent years, maintaining exposure to multiple sources of return remains a cornerstone of prudent long-term investing. And for all of us at Marquette Associates, let’s hope the phrase “no more free lunch” never extends beyond portfolio theory and into the lunchroom!
Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

09.08.2026
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…

08.31.2026
Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears…

08.24.2026
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…

08.17.2026
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…

08.10.2026
After reaching nearly ¥164 per dollar, its weakest level in roughly four decades, the yen had become a source of…

08.03.2026
In the cinematic masterpiece Rocky IV, Rocky gets dazed by his opponent, Captain Ivan Drago, and complains that he sees…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >