Evan Frazier, CFA, CAIA
Senior Research Analyst


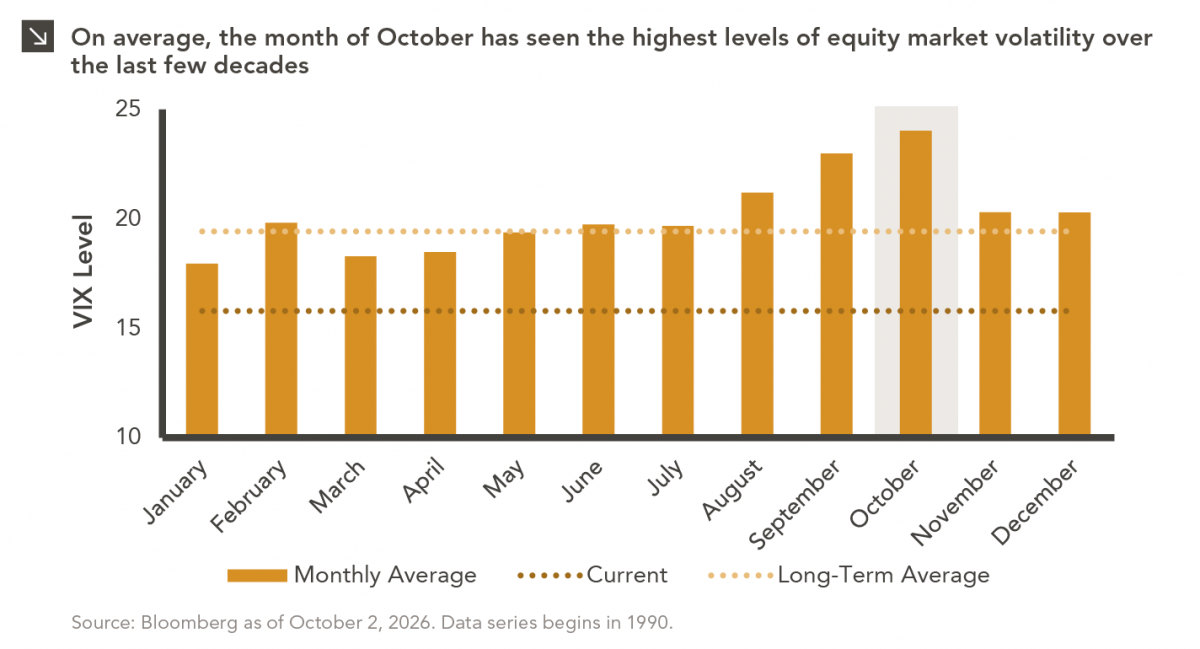
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up at front doors demanding candy, but rather a potential uptick in market volatility, which has remained relatively muted over the last several months. Indeed, the CBOE Volatility Index (“VIX”), which measures expectations for U.S. stock market volatility over the next 30 days based on S&P 500 Index option prices, currently sits at roughly 15.8, placing it close to the lowest third of observations since 1990. Additionally, the VIX has not climbed above 25 since April, suggesting that investors are not currently spooked about the near-term outlook for U.S. equities. It is worth noting, however, that October has historically seen the highest average VIX levels of any month since 1990. These dynamics can be observed in the chart above.
Often referred to as the market’s “fear gauge,” the VIX tends to rise when investors expect greater market uncertainty and fall when expected volatility is lower. A few factors may help explain why the VIX has tended to be higher in October. For instance, U.S. midterm and presidential election cycles can contribute to greater uncertainty during the fall, as investors assess potential changes to fiscal, regulatory, and trade policy that could result from a change in political leadership. To that point, CBOE has observed higher implied volatility around Election Day, including in 2024 as the presidential election approached. It is important to point out that October’s historical volatility has also been heavily influenced by major market events, particularly the Global Financial Crisis. Specifically, the VIX reached an intra-month high of roughly 89.5 on October 24, 2008, as the crisis intensified, and spent most of that month above 60. Additionally, although not captured in the chart above, the infamous “Black Monday” crash of 1987 that saw the S&P 500 Index plummet by more than 20% occurred on October 19. These data points suggest that at least part of October’s spooky reputation is attributable to exogenous market shocks rather than a predictable seasonal effect specific to the month itself.
While October has historically been associated with elevated volatility, market gyrations in the weeks ahead are by no means inevitable. Corporate fundamentals remain relatively strong, providing an important foundation for equity markets even as investors navigate a range of uncertainties. At the same time, the upcoming midterm elections and elevated market valuations could create greater sensitivity to economic developments, potentially contributing to periods of increased volatility. Ultimately, while October may have a reputation for spooking investors, the prospect of heightened volatility should not distract investors from their long-term strategic allocations or lead them to make short-term investment decisions based on seasonal market fears.
Print PDF
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.26.2026
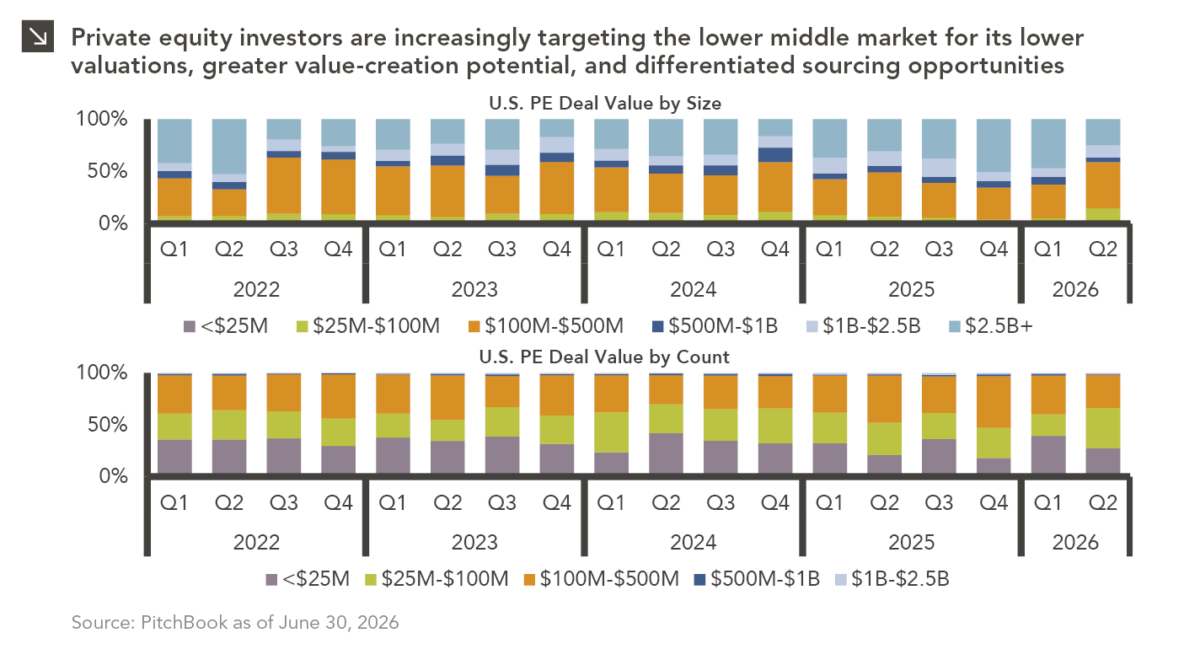
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…
10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
10.19.2026
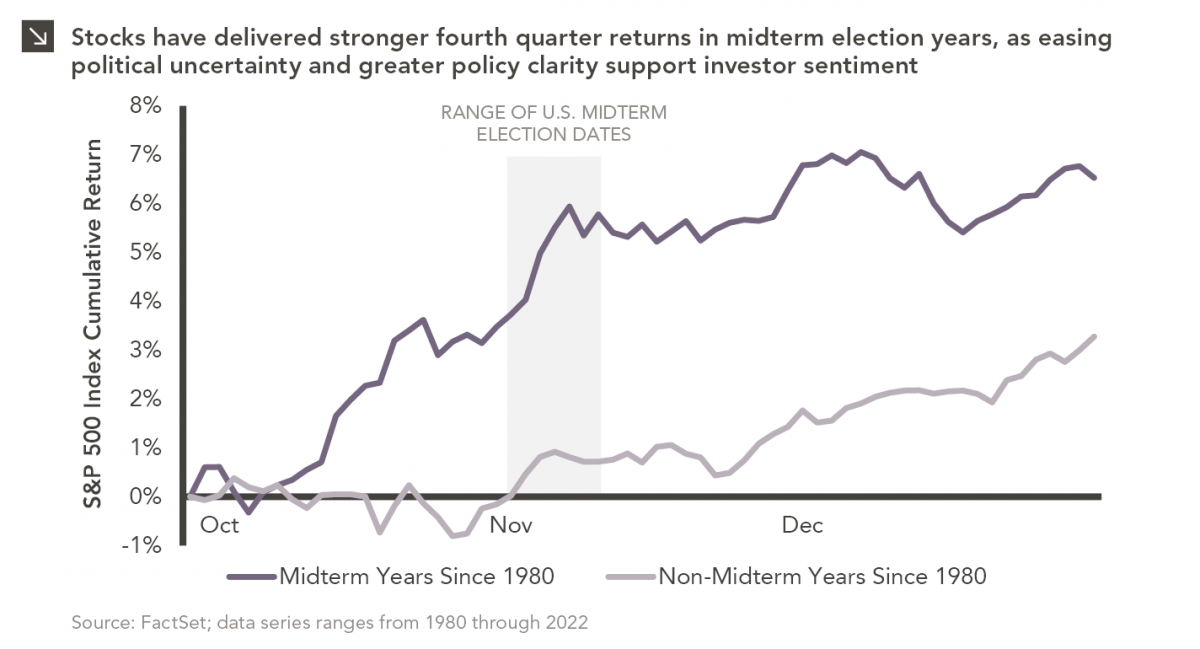
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.12.2026
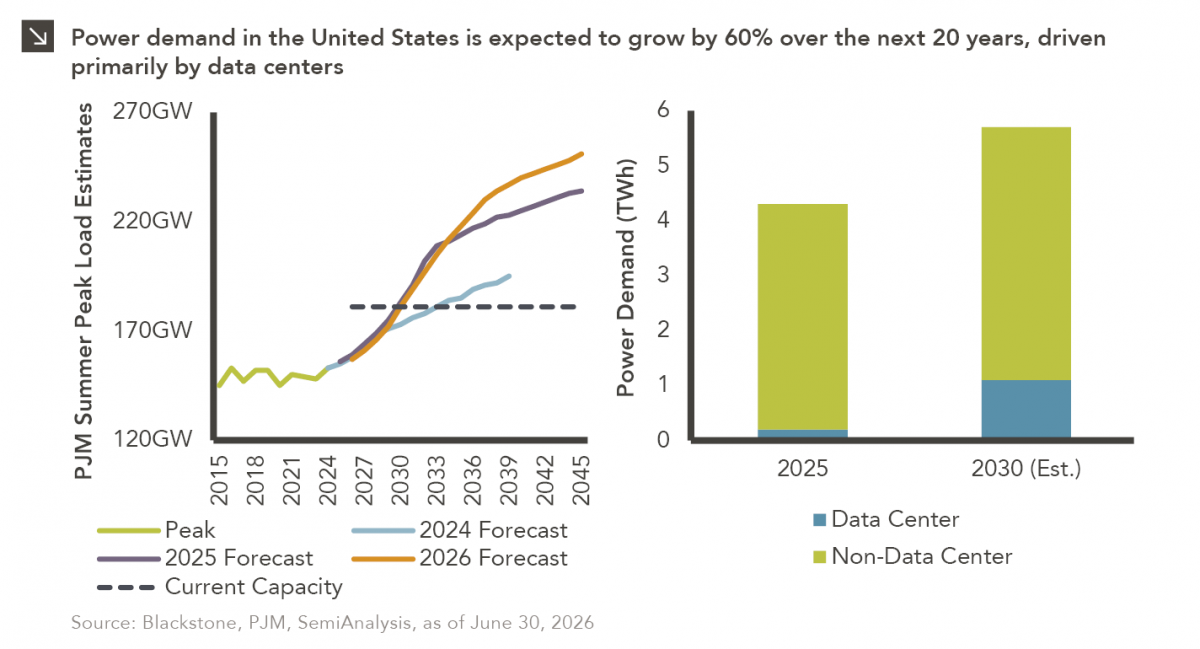
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
09.28.2026
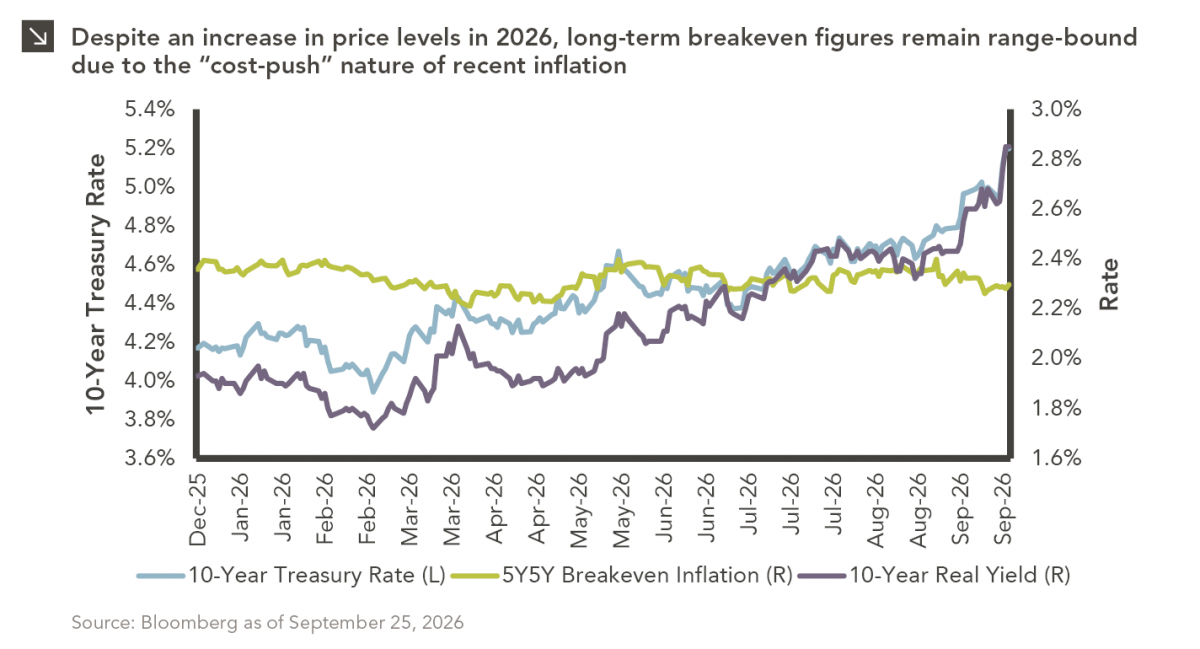
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >