No Reservations

March 24, 2020 | Nat Kellogg, CFA, President

This week’s chart examines the demand for restaurant reservations, both in the U.S. and across the globe, measured by reservation booking activity on OpenTable, a service that allows users to book restaurant reservations online or through its app. Overall reservation booking activity started to slow noticeably at the beginning of March and then cratered as state after state closed schools, urged citizens to work from home, and then eventually closed all restaurants and bars for dine-in service. This is a compelling “real-time” indication of the scope and scale of the economic slowdown caused by the coronavirus.

While restaurants are only one small piece of the economy, they are an excellent gauge of discretionary consumer spending and provide employment to over 14 million restaurant workers across the United States. Although OpenTable’s largest market is here in the U.S., their data also indicates a similarly severe slowdown in global activity. The longer quarantines across the country (and around the globe) last, the more painful the effects on the restaurant industry, and the broader U.S. economy, will be.

Print PDF > No Reservations


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Nat Kellogg, CFA
President

Get to Know Nat

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

10.08.2026

3Q 2026 Market Insights Webinar

LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

Line chart showing 10-year U.S. Treasury rate, 5-year/5-year breakeven inflation rate, and 10-year real yield from December 2025 through September 2026. The left axis shows rates from 3.6% to 5.4%, and the right axis from 1.6% to 3.0%. The Treasury rate and real yield rise notably in late 2026, while the breakeven inflation rate remains relatively range-bound around 2.3%–2.4%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.28.2026

Getting Real on Inflation

The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

Dual-axis line chart comparing LBO/M&A/Recapitalization Activity, its average level, and the SOFR (90-Day) rate from 3Q18 through 2Q26. LBO/M&A/Recapitalization Activity ranges from approximately $0 billion to $100 billion, while SOFR ranges from 0% to approximately 5%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.21.2026

Let’s Make a Deal

For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

Line chart comparing annualized return and annualized risk for stock-bond portfolio combinations from 1976-2019 and 2020-2026. Two lines show the range of return and risk outcomes across portfolio allocations during each period. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.14.2026

No More Free Lunch?

There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
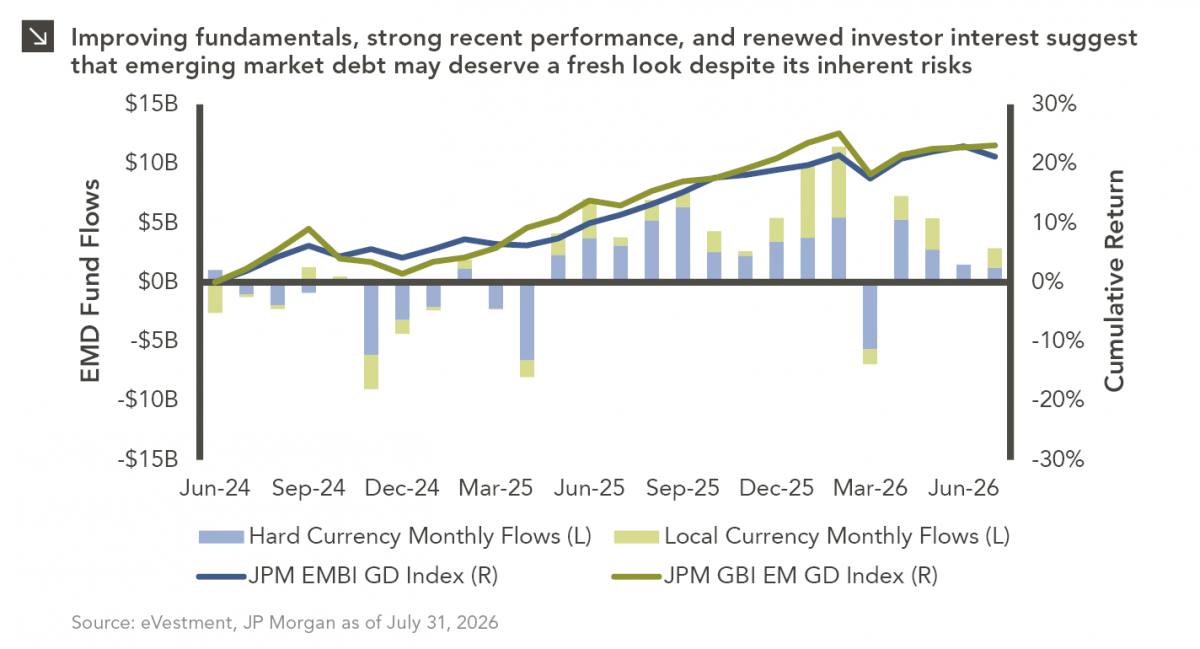
Combination stacked column and line chart comparing EMD fund flows (columns) and index cumulative returns (lines), June 2024 to present. Indices used: JPM EMBI GD Index and JPM GBI EM GD Index. Since May 2025, Monthly Flows have been positive, with the exception of March 2026. Most recent datapoint: July 31, 2026 Hard Currency Flows $1.2B, Local Currency $1.6B, JPM EMBI GD Index at 21.2%, JPM GBI EM GD Index at 23.1%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.08.2026

EMD’s Second Chance?

Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >