The Best and Worst of Times

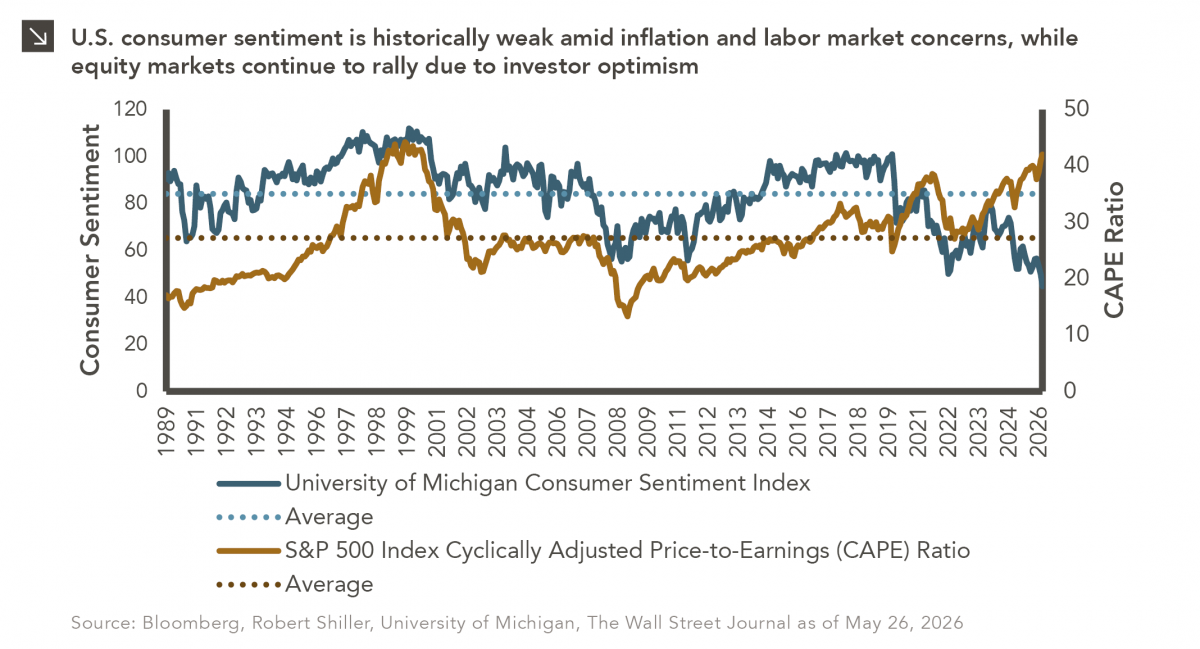
The classic novel A Tale of Two Cities by Charles Dickens begins with the line “It was the best of times, it was the worst of times…” While Dickens was describing the extreme contradictions of the late 18th century leading up to the French Revolution (i.e., comfort for the aristocracy and hardship for the poor), this line could just as easily apply to the current economic environment in the United States, which is marked by a stark divergence between consumer confidence and investor behavior. Specifically, recent University of Michigan consumer sentiment readings have fallen to some of the weakest levels in decades, reflecting persistent frustration on the part of many Americans over inflation, elevated interest rates, high gasoline prices, and job security. Consumers remain particularly sensitive to the cumulative impact of several years of higher prices, even as headline inflation has moderated from its post-pandemic peaks. Surveys from both the University of Michigan and the Conference Board suggest U.S. households are increasingly worried about future economic conditions and weakness in the labor market. At the same time, equity markets have largely shaken off these concerns given enthusiasm surrounding artificial intelligence and expectations for longer-term productivity gains. Indeed, the S&P 500 Index has notched gains of more than 17% in each of the last three full calendar years and has advanced more than 9% in 2026 as of this writing. This strong performance has led to higher equity market valuations. As can be seen in this week’s chart, the Shiller Cyclically Adjusted Price-to-Earnings (CAPE) Ratio for the S&P 500 Index, which compares prices to average inflation-adjusted earnings over the prior 10 years to smooth out short-term volatility, sits at roughly 42. This figure is well above historical average levels and signals that investors continue to pay a significant premium for future earnings growth despite weaker consumer sentiment. Many have described this dynamic as a “tale of two markets,” as investors reward companies with outsized earnings potential and the ability to generate technological disruption even as households cut back on discretionary spending and grow more cautious about the economy.

A major driver of the divergence described above is the way in which financial asset ownership is distributed in the United States. A recent estimate from the Federal Reserve indicates that the top 10% of American households own roughly 90% of all U.S. corporate equities and mutual fund shares, meaning recent market gains have created a wealth effect that continues to support spending among affluent consumers, even as lower- and middle-income households face significant pressures. This divergence also highlights the forward-looking nature of financial markets, as equity investors are often pricing in anticipated earnings growth and future monetary policy as opposed to current economic conditions. Most consumers, on the other hand, respond more directly to present-day realities such as grocery bills, gasoline prices, and the perceived stability of the labor market. Whether this sentiment gap ultimately closes due to consumer confidence that is recalled to life or equity valuations that face the guillotine of market repricing remains one of the key questions facing investors in the near term.
This Too Shall Reconstitute

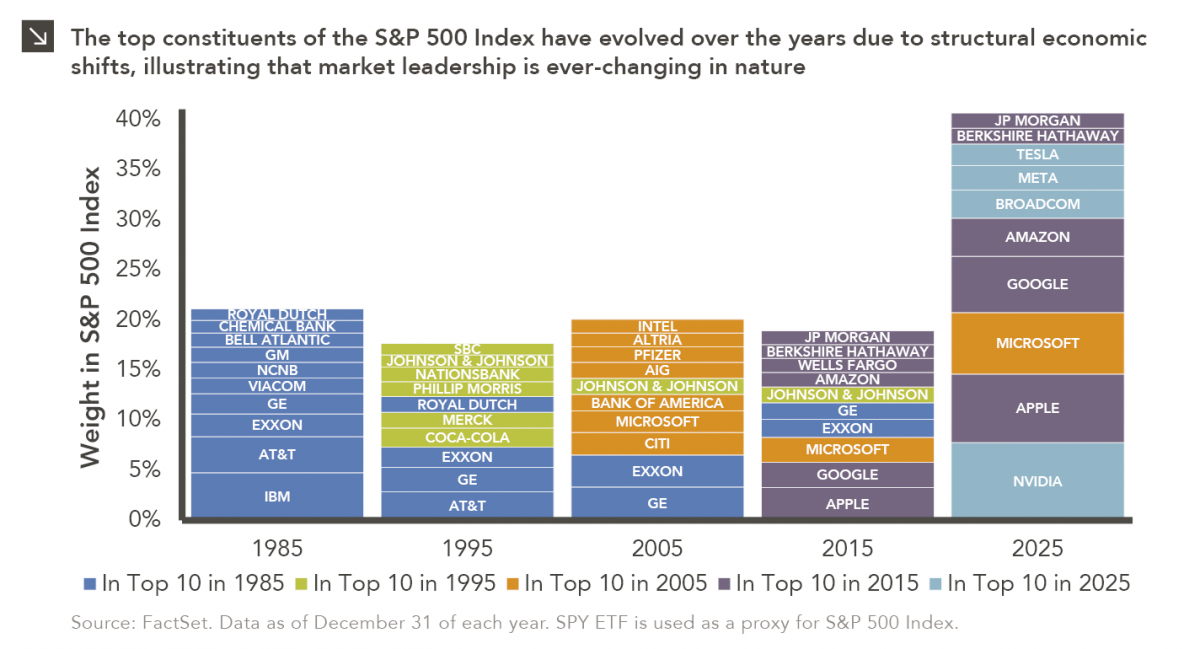
Rooted in medieval Persian Sufi thought, the adage “this too shall pass” speaks to the fleeting and impermanent nature of the human condition. For investors, this aphorism can serve as a useful framework for understanding the constantly evolving composition of the upper end of the U.S. equity market. As this week’s chart shows, the top 10 constituents of the S&P 500 Index have changed dramatically over the last 40 years, with each new decade seeing both additions to and subtractions from this basket of companies.

In 1985, the top of the S&P 500 Index was heavily weighted toward industrial conglomerates, energy producers, and legacy financial and telecommunications firms such as IBM, Exxon, AT&T, and General Electric. This composition reflected an economy still anchored in manufacturing, physical infrastructure, and regulated industries with durable but relatively slow-moving competitive dynamics. Capital intensity, domestic scale, and regulatory barriers to entry helped entrench incumbents, allowing a small set of diversified conglomerates and commodity-linked businesses to dominate equity indices. As can be observed in this week’s chart, the top 10 constituents represented roughly 21% of the S&P 500 Index in 1985. In contrast, the top 10 constituents at the end of last year represented more than 40% of the benchmark, with technology-oriented companies like NVIDIA, Apple, Microsoft, Alphabet, Amazon, and Meta topping the benchmark and accounting for an outsized share of index earnings and returns in recent years.

The transition between these two regimes did not occur abruptly but rather through decades of structural changes, including the rise of the digital economy, the decline in manufacturing’s share of GDP, and the increasing importance of intangible assets such as software, data, and intellectual property. Indeed, the 1990s and early 2000s saw the rise and consolidation of the internet economy, which led to the reshaping of information, communication, and commerce. The years following the Global Financial Crisis further accelerated the dominance of scalable, asset-light business models, while low interest rates and abundant liquidity disproportionately benefited high-growth technology firms. At the same time, several former index leaders either stagnated, were disrupted, or lost relative economic relevance, leading to a gradual but persistent turnover at the top of the index.

Against this backdrop, the current composition of the S&P 500 Index should not be viewed as fixed, but rather as a snapshot of a specific moment in time. If history is any indication, the next decade will likely bring another reshuffling of top index constituents as new technologies, industries, and business models emerge. For investors, this suggests that maintaining broadly diversified equity exposure while remaining disciplined around rebalancing is prudent, as market leadership, however dominant it appears at a given time, has historically been transient rather than permanent.

1Q 2026 Market Insights Webinar

This video is a recording of a live webinar held April 16 by Marquette’s research team analyzing the first quarter across the economy and various asset classes as well as themes we’ll be monitoring in the coming months.

Our quarterly Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real assets, and private markets, with commentary by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
James Torgerson, Senior Research Analyst
Fred Huang, Research Analyst
David Hernandez, CFA, Director of Traditional Manager Search
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Hayley McCollum, Senior Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

If you have any questions, please send our team an email.


A Bug in the Software

Recent market dynamics in the software sector reflect a sharp shift in investor sentiment driven primarily by concerns that advances in artificial intelligence could fundamentally disrupt traditional software business models. Public software-linked equities have sold off broadly (even as many companies continue to deliver solid earnings) because investors are increasingly focused on long-term structural risks rather than near-term financial performance. Indeed, estimates for longer-term earnings growth for these businesses have started to decline despite stable or improving near-term outlooks, highlighting growing skepticism around the durability of pricing power, competitive moats, and growth trajectories in an AI-enabled environment. Since the end of October, the S&P North American Technology Software Index has fallen by roughly 30%. These concerns have now spread beyond equities into credit markets, where leveraged loan investors are rapidly reducing exposure to software-related borrowers. Many software loans that entered 2026 priced at or near par have since declined as investors reassess the sector’s credit risk profile, reflecting fears that AI-driven disruption could weaken cash flows and increase default risk for highly leveraged issuers. Specifically, the Morningstar LSTA U.S. Leveraged Loan Index has dropped by around 6% since the start of 2026.

This repricing across equity and credit markets underscores a key shift in sentiment. Software, long viewed as one of the most predictable and resilient sectors of the economy due to recurring revenue models and high margins, is now facing simultaneous multiple compression in equities and widening spreads in credit. While fundamentals remain relatively intact today, markets are increasingly discounting a wider range of potential outcomes for software-linked businesses, creating heightened volatility and a more selective environment in which investors are demanding clear evidence of AI resilience and sustainable competitive differentiation.

The Seller Becomes the Buyer

Most have traditionally viewed a successful exit for a venture-backed start-up as either an IPO or an acquisition by a larger strategic or public company. That long-standing dynamic is gradually shifting, as start-ups are now more active than ever as acquirers. Indeed, what was once a buyer landscape dominated by strategics and public corporations now increasingly includes venture-backed firms. According to PitchBook-NVCA data, VC-backed buyers accounted for more than 38% of total U.S. venture M&A activity last year, up from roughly 20% a decade ago, with 2025 marking seven consecutive years of increasing participation. Specifically, more than 387 start-ups were acquired by venture-backed companies last year, compared with 177 in 2015. Although overall exit volumes remain below 2021 peak levels, the steady rise in startup-led acquisitions reflects a structural shift toward internal consolidation within the venture ecosystem.

The drivers behind this shift are largely pragmatic, as capital remains available but far more selective. Growth equity investors are increasingly concentrated within perceived category leaders, while companies that fall slightly below that threshold face a more challenging fundraising environment. For scaling start-ups that have survived earlier rounds of capital selection, acquisitions can serve as an efficient strategic accelerant. Rather than depleting cash reserves to build adjacent features, expand geographically, or acquire customers organically, management teams can accelerate these objectives through M&A, adding revenue, product capabilities, or talent in a single transaction. At the same time, the bar for IPO readiness has risen materially in the last five years, as public investors are increasingly prioritizing profitability, operating leverage, and durable revenue growth. For venture-backed companies aiming to meet these standards, combining with a competitor or complementary platform can create scale and margin expansion more quickly than standalone execution. In some cases, consolidation represents the most rational path forward in a more disciplined capital cycle. This trend is visible at the upper end of the market as well. For instance, OpenAI completed five acquisitions across hardware design, experimentation tooling, fintech AI capabilities, and model infrastructure in 2025 alone. The fact that one of the world’s most valuable private companies is actively using M&A as a growth lever reinforces the idea that an acquisition is no longer solely a means of exit but increasingly a tool for expansion.

While it remains too early to declare a permanent transformation in venture markets, it is clear start-up-led consolidation is becoming more common and strategically meaningful. As companies remain private for longer and develop greater operational scale, their roles as acquirers may continue to expand.

Precious Metals Lose Their Luster… Perhaps

Precious metals have been going on a magnificent run in recent years. Specifically, gold moved from $1,898/ounce at the end of 2020 to $5,375/ounce on January 29 of this year, which represents a gain of 181%. During that same time, silver exhibited a more volatile but highly correlated return pattern, moving from $26/ounce to $116/ounce for a gain of 338%. Then came Friday, January 30. On that day, gold dropped more than 12%, its biggest intraday decline since the early 1980s. Silver plunged by a staggering 36%, a record intraday decline for the metal. The fall continued in February, with gold and silver falling to $4,661/ounce and $79/ounce, respectively. Markets have bounced back somewhat in recent days, with gold climbing by roughly 6% and 3% on Tuesday and Wednesday of last week, respectively. Silver advanced on those days as well. Despite this recent pop, many investors are asking the following question given the sharp decline in gold and silver: Have precious metals lost their luster?

To answer this question, it is worthwhile to first outline the reasons for the run-up in gold and silver over the last several years. A primary factor driving strong precious metal performance is global inflation and geopolitical instability (e.g., tensions between the U.S., Russia, China, and the Middle East) that has pushed investors to seek safety in more traditional stores of value. Tariffs and trade-related conflicts have exacerbated this flight to perceived safety. Additionally, developed economies continue to run significant budget shortfalls, leading investors to gold over bonds as governments continue to issue debt to fund deficits. Individual investors are not the only ones that are adding to their gold reserves, as central banks around the world have been purchasing record amounts of gold in recent years as part of a push toward tangible asset ownership. Finally, there have been tailwinds specific to silver, including a structural deficit, thinner trading markets, and its usage in AI infrastructure, data centers, electric vehicles, and solar panels.

After the rally came the fall on January 30, when the Trump administration tapped Kevin Warsh to lead the Federal Reserve. Traders viewed Warsh as the toughest inflation fighter among the finalists for the position, and his nomination increased expectations of U.S. dollar strengthening and weaker precious metals in dollar terms. The slide in precious metals may have been exacerbated by a gamma squeeze, in which dealers must sell positions as prices fall to maintain balanced portfolios.
Fast markets make commentary quickly obsolete, and it is possible that metals markets will exhibit additional volatility in the weeks ahead. This volatility, as well as potential storage costs and the speculative nature of the space, are drawbacks of precious metals investing, and investors should treat commodities like gold and silver with caution given these risks. Time will tell if gold and silver have indeed lost their luster.

Seventy-Five Horses and Two Pieces of Plastic

Anyone who has gone snowmobiling knows it can be simultaneously exhilarating and terrifying. Throttling across snow and through a forest powered by a 75-horsepower engine with two plastic skis to steer makes it hard to feel like one has complete control; 30 mph in the open air feels more like 100!

Nonetheless, operating a snowmobile is pretty straightforward: The throttle is a right-thumb button, the brake is a left-hand squeeze lever. Beyond those two controls, it’s up to the driver to effectively navigate the trail, with the critical concession that the terrain is out of anyone’s complete control. Which brings me to our 2026 market outlook.

The “throttles” for portfolios are the usual constituents: equities, below investment grade credit, and private markets. The “brakes” are investment grade fixed income, particularly Treasuries which can slow a portfolio’s losses if the market tumbles. The terrain is naturally the actual path that each of these asset classes will follow in 2026. Since 2022 the equity market ride has been mostly exhilarating, save for some of the terrifying moments like the market dip after Liberation Day. But that’s in the rearview mirror, and the focus is what is around the bend. Will the thrill continue, or should we ease up on the throttle?

Concentrating on Market Concentration

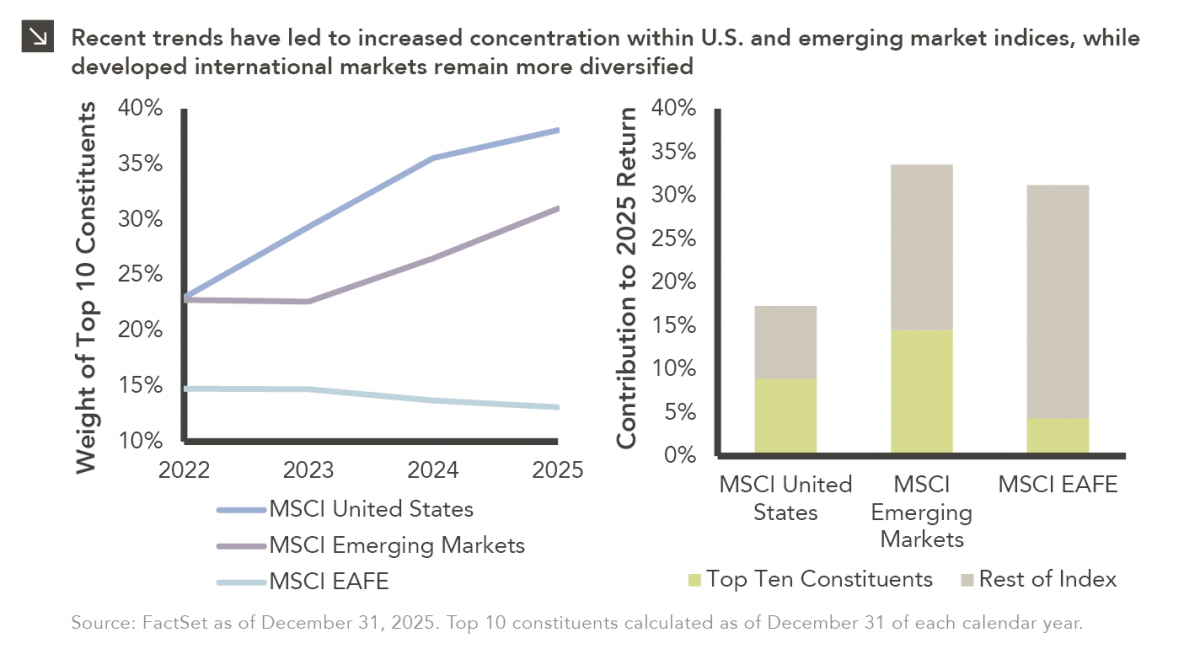
Last week, Alphabet joined NVIDIA, Microsoft and Apple as the only companies to ever reach a market capitalization of $4 trillion. The growth of these and other U.S. mega-cap technology companies has completely changed the composition of indices that measure the domestic equity market. Indeed, the weight of the top 10 constituents of the MSCI United States Index (which is comprised of large- and mid-cap stocks) sat at roughly 23% just three years ago. At the end of last year, however, that figure sat closer to 38%. As can be seen above, this concentration has resulted in a handful of stocks driving a significant share of overall index returns in recent periods. Interestingly, the theme of market concentration is not exclusive to domestic indices. For instance, companies in China, Taiwan, and South Korea have helped provide the materials required for the artificial intelligence boom, and the growth of these businesses has led to higher levels of concentration for the MSCI Emerging Markets index. The top 10 constituents now represent slightly less than one-third of this index, and TSMC, the largest producer of semiconductors in the world, notably comprises roughly 12% of the benchmark. Similar to trends within domestic markets, these top constituents had an outsized impact on the return of the MSCI Emerging Markets Index in 2025.

Interestingly, the MSCI EAFE Index, which is comprised of non-U.S. developed markets large- and mid-cap stocks, has not followed these same trends, with the weight of its top 10 constituents actually decreasing in recent years. While its largest holding is ASML, a supplier for the semiconductor industry, this benchmark is not nearly as heavily tilted towards the AI boom as domestic and emerging markets indices. For this reason, developed international markets could be a stronger source of diversification for investors moving forward.

Brains Over Brawn?

The development of artificial intelligence is advancing along two largely distinct paths. The first centers on generative AI powered by large language models, with the long-term objective of creating systems that can reason across domains at levels superior to those of human beings. The second focuses on embodied intelligence (i.e., robotics). In this space, the objective is not abstract reasoning but rather the deployment of capable machines that can operate effectively in the physical world. Over the last five years, capital and attention have overwhelmingly gravitated toward companies involved in generative AI, with the Bloomberg Artificial Intelligence Index up a staggering 276% in that time. Robotics, by comparison, has been widely viewed as a longer-dated theme, with the Bloomberg Robotics Index up only 77% over that same period (even less than the S&P 500 Index return of 134%). These dynamics can be observed in this week’s chart.

Going forward, there are reasons to believe that this performance trend may shift in the years ahead. For instance, human-level general intelligence could be far more distant than markets currently assume, and language models may not prove sufficient to reach it. At the same time, practical robots (e.g., warehouse automation, humanoid assistants, etc.) appear closer to commercial reality than previously believed, particularly in aging societies facing persistent labor shortages. One possible accelerant for robotics companies in the years ahead is the use of advanced simulation. By training in virtual environments, robots can acquire motor skills and coordination far more rapidly than through physical trial and error alone, potentially pulling forward adoption timelines relative to current investor expectations. Importantly, transformative impact does not require robots to achieve artificial general intelligence but rather functional capability (i.e., the ability to move objects, operate safely, and sustain useful work with sufficient battery life). Commercial momentum in robotics is already building. In 2024, for example, Agility Robotics opened a manufacturing facility in Oregon with capacity to produce up to 10,000 humanoid units annually, and Amazon has now begun testing Agility’s robots in its warehouses. Additionally, companies like Tesla are showcasing humanoid prototypes performing increasingly fluid physical tasks, and BYD has signaled interest in future household robotics. While price points remain prohibitive for mass adoption today, several structural forces are converging to improve the economics of robotics. Manufacturing costs are declining as scaling drives down prices for components like sensors and actuators, while improvements in AI models are enhancing robotic perception and control. Taken in tandem with the fact that generative AI leaders are currently investing heavily in costly, power-hungry data centers, it is fair to say that a once slower-moving, less glamorous segment of the AI ecosystem may now benefit from relative capital efficiency.

Despite these developments, markets continue to assign a significant valuation premium to generative AI over robotics, which can also be observed in the chart above. Factor analysis helps explain part of the gap, as AI-heavy indexes skew toward momentum and growth while robotics-oriented benchmarks exhibit greater exposure to value, quality, and, in some cases, even dividend income. Further, the generative AI complex is dominated by large technology platforms including Alphabet, Microsoft, and NVIDIA, whereas robotics companies tend to be more industrial in nature (e.g., automation specialists, automakers, and emerging consumer-robotics firms). This valuation disconnect suggests that investors may be overemphasizing long-term breakthroughs in cognition while underappreciating near-term progress in physical automation, especially as physical robots transition from research environments into factories, homes, and hospitals. Indeed, while much of today’s excitement centers on artificial brains, it may ultimately be robotic brawn that drives the next leg of growth within the technology sector.

Big “Issues” for Big Tech

While technology-oriented firms have made their presence known in equity markets for several years, these companies have made waves in the fixed income space recently as well. Companies such as Alphabet, Meta, and Oracle, which in the past have funded initiatives via balance sheet cash, have increasingly turned to the bond market to finance the buildout of AI-related infrastructure. Specifically, a total of nearly $240 billion worth of investment-grade bonds have been sold by technology giants on a year-to-date basis through the end of November. Some notable deals in 2025 include Meta’s $30 billion bond sale, the largest in the U.S. high-grade market this year, Oracle’s $18 billion issuance in September, and Alphabet’s deal that raised $17.5 billion in the U.S. and another €6.5 billion (roughly $7.5 billion) in Europe.

This surge in supply carries meaningful implications for the broader investment-grade corporate market, which is one of the most heavily traded areas of fixed income. For instance, the sheer volume of new issuance from technology companies can put upward pressure on corporate spreads as investors demand slightly higher yields (despite the strong balance sheets and generally low leverage of these firms). There is also the question of the potential return on AI-related spending (or lack thereof). Indeed, a recent MIT study found that around 95% of companies have yet to see any meaningful payoff from their generative AI efforts. At the same time, investors and creditors are growing more cautious, increasing their use of derivatives designed to pay out if specific technology firms fail to meet their debt obligations. That said, investment in AI-related infrastructure seems likely to continue at full speed in the years ahead, meaning technology firms may continue to tap the investment-grade market for financing.