Industrial Real Estate: Smaller is Better?

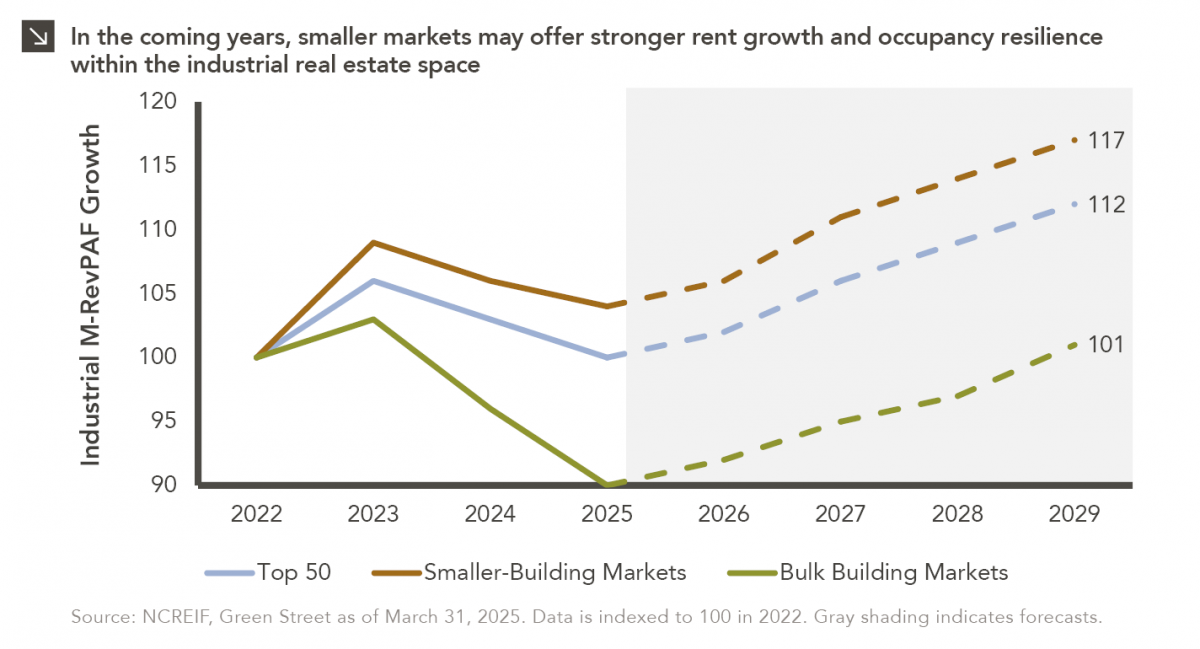
This week’s chart compares realized and expected Market Revenue per Available Foot (“M-RevPAF”) growth within the industrial real estate space across three segments: The top 50 markets, smaller-building markets, and bulk building markets. M-RevPAF blends rent and occupancy into a single metric, providing a comprehensive view of market revenue performance.

Over the past several years, elevated new supply in low-barrier bulk distribution markets has pressured occupancy and rents, causing this segment to lag both smaller-building markets and the Top 50 diversified index. That gap is expected to widen further by 2029, as smaller-building markets are projected to deliver roughly five percentage points of additional cumulative revenue growth relative to bulk markets. For instance, smaller-building markets like those in infill and supply-constrained areas such as South Florida are positioned to capture stronger rent growth and maintain higher occupancy rates due to demand dynamics and limited new deliveries. Conversely, bulk distribution markets are still digesting significant deliveries from the 2021-2023 development cycle, which may keep vacancies elevated and rent growth muted for several years.

These forecasts highlight the potential for a meaningful divergence in performance across industrial subsectors, stressing the need for discipline and precision when it comes to capital allocation by asset managers. Allocations toward smaller markets can help enhance portfolio resilience and capture outperformance relative to bulk distribution markets, where managers should be employing more conservative underwriting (assuming longer lease-up periods, requiring wider exit cap rates to compensate for slower NOI growth, etc.). A diversified approach that combines Top 50 markets with targeted exposures to smaller-building strategies may offer the best balance between growth and stability for investors in the years ahead.
2025 Investment Symposium

Watch the flash talks from Marquette’s 2025 Investment Symposium livestream on September 26 in the player below — use the upper-right list icon to access a specific presentation.


Please feel free to reach out to any of the presenters should you have any questions.

What’s It All Worth?

In private markets, secondary transactions have increasingly gained attention and acceptance as a viable liquidity option for both general partners (“GPs”) and limited partners (“LPs”). During the first half of 2025, secondary market volume reached record levels, surpassing $100 billion for the first time in history. Specifically, volume totaled $102 billion in the first six months of the year, with a nearly even split between LP-led (53%) and GP-led (47%) transactions. To put this in perspective, secondary transaction volume for the entirety of 2022 was $103 billion. Although dry powder has declined in recent months — from $216 billion in 2024 to $171 billion — fundraising is expected to more than offset this decrease, with $218 billion projected to be raised over the next year.

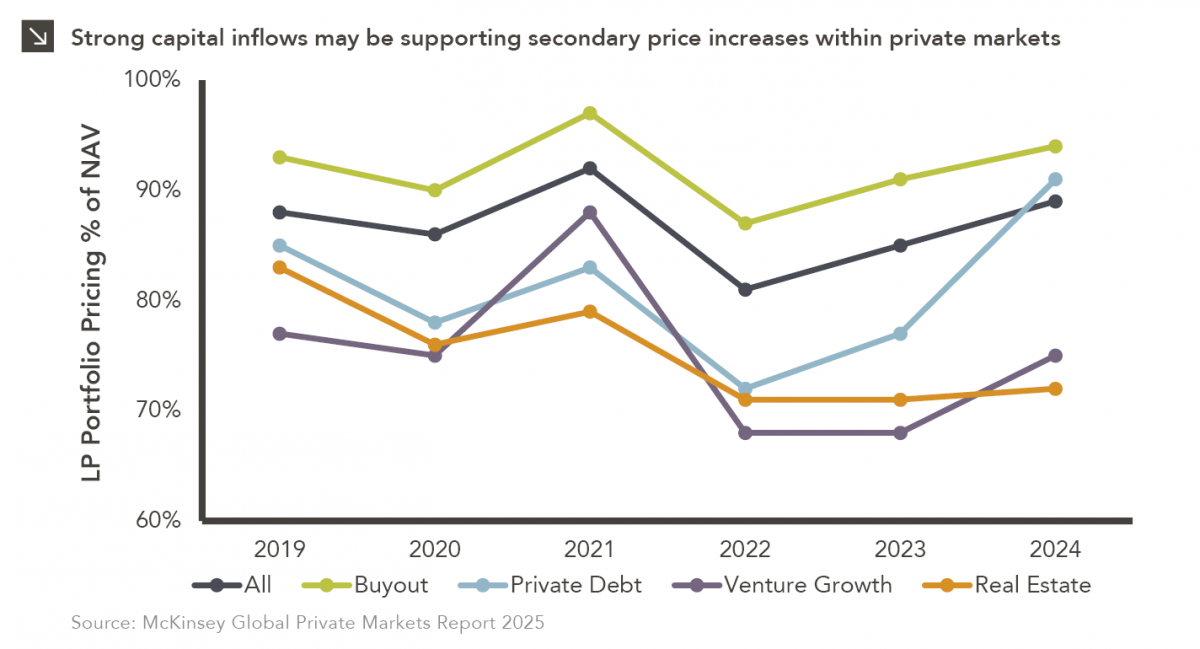
As is common with most asset classes, increased market participation leads to more capital being raised and deployed, which, in turn, drives asset prices higher. The secondary market follows this same trend. Typically, secondary transactions are priced at a discount to the net asset value (“NAV”) of the assets or stakes being sold. However, secondary pricing across all private asset classes increased in 2024, reaching 89% of NAV (up from 85% in 2023). Buyout secondaries saw the highest pricing last year, trading at 94% of NAV, while pricing of private debt secondaries jumped from 77% of NAV in 2023 to 91% in 2024. In contrast, real estate secondaries traded at the lowest percentage of NAV, settling at 72% in 2024. This figure is more consistent with the 71% trading value exhibited by real estate secondaries in 2022 and 2023.

This brings us to the central question of this piece: What’s it all worth? Simply put, whatever someone is willing to pay! But how do we value an asset purchased at a discount? Can we trust the original valuation? Historically, secondary buyers have tended to mark acquired assets up relative to the previous owner’s NAV shortly after the transaction closes, but is this a fair and accurate way to value an asset? If buyers conduct thorough due diligence, their own assessments of a company or portfolio will inform their willingness to pay market-clearing prices, meaning pricing is not determined solely by the current value of an asset. Indeed, buyer perspectives on future growth potential, exit opportunities, and comparable market transactions all influence secondary market pricing. Additionally, recent strong capital inflow for the asset class may be putting pressure on acquirers to put money to work, potentially contributing to the recent uptick in pricing.

2025 Halftime Market Insights

This video is a recording of a live webinar held July 17 by Marquette’s research team analyzing the first half of the year across the economy and various asset classes as well as themes we’ll be monitoring through the rest of 2025.


Our quarterly Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real assets, and private markets, with commentary by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
Frank Valle, CFA, CAIA, Associate Director of Fixed Income
James Torgerson, Senior Research Analyst
Catherine Hillier, Senior Research Analyst
David Hernandez, CFA, Director of Traditional Manager Search
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Amy Miller, Associate Director of Private Equity
Chad Sheaffer, CFA, CAIA Senior Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

If you have any questions, please send our team an email.

The Hidden Cost of NOI

Capital expenditure is a crucial yet sometimes underappreciated component in real estate underwriting, as it directly eats into the cash flows available to investors. While a given sector may benefit from certain tailwinds (e.g., demographic shifts, technological adoption, etc.), elevated capital expenditure requirements can materially impair the growth and durability of net operating income. This is particularly relevant in spaces like life science, medical office, and data centers, where structural demand is strong but operational and replacement costs are high.

A clear takeaway from this week’s chart is the connection between GDP-driven sectors and elevated capital expenditure burdens, with both the office and hotel spaces standing out as significantly more capital-intensive than other property types. Specifically, the office sector has suffered sharp valuation declines in recent years, but its capital expenditure challenges were apparent even before that correction. Aging building stock, tenant improvement costs, and escalating obsolescence make net operating income growth difficult within the office space, especially for older assets in secondary markets. This structural drag further complicates recovery prospects for the sector in a post-pandemic, hybrid work environment. On the other end of the spectrum are self-storage assets, with capital expenditure at only 7.7% of net operating income. The low capital intensity, scalability, and operational simplicity of the self-storage space make it one of the most capital-efficient sectors within real estate and especially attractive given the uncertain macroeconomic environment.

In conclusion, while sectors like office or retail may exemplify industry innovation or trend leadership, select opportunities still exist within these spaces. Diligent asset selection that focuses on location, tenant quality, lease structure, and physical upgrades can lead to attractive risk-adjusted returns, even within sectors that exhibit higher levels of capital expenditure. In a yield-starved world, nuanced underwriting and asset-level differentiation remain essential when it comes to extracting value from these spaces.

As Real Estate Finds Its Bottom, Alternative Sectors Become More Prominent

Since the onset of the pandemic, the commercial real estate market has experienced significant volatility — first benefiting from a post-pandemic surge, then grappling with a sharp downturn, and now showing signs of stabilization. With the third quarter of 2024 marking the first quarter of positive returns after eight consecutive quarters of losses, the fourth quarter performance added to the case that the asset class has found a floor. This newsletter outlines recent improvements not only across traditional sectors but also an expanding set of alternative property sectors. These alternatives, which include data centers, life sciences facilities, self-storage, and senior housing, reflect the changing composition of institutional real estate portfolios and the growing emphasis on diversification beyond the traditional core sectors. We also explore drivers of demand, specific opportunities in alternative real estate, and value-added real estate.

1Q 2025 Market Insights

This video is a recording of a live webinar held April 16 by Marquette’s research team analyzing the first quarter of 2025 (and recent weeks) across the economy and various asset classes as well as themes we’ll be monitoring in the coming months.

Our Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real estate, infrastructure, private equity, and private credit, with presentations by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
Frank Valle, CFA, CAIA, Associate Director of Fixed Income
Catherine Hillier, Senior Research Analyst
David Hernandez, CFA, Director of Traditional Manager Search
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Hayley McCollum, Senior Research Analyst
Chad Sheaffer, CFA, CAIA Senior Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

If you have any questions, please send our team an email.


Bracing for Stagflation

As markets swirl and stagflation fears mount, what should investors do?
Our newsletter last week outlined the broad context of President Trump’s new tariff policy as well as the most notable market impacts. Granted, the news seems to change daily, as does the market’s reaction; trying to pen a targeted newsletter is an almost worthless endeavor because by the time the ink has dried, markets have shifted due to another policy pivot. In the short term, the omnipresent cloud of uncertainty will continue to drive market volatility and investor sentiment. The best recipe for investors to weather this storm is patience and discipline, both of which can be difficult to come by in the current environment.

As we step back and take a longer-term view of the future, however, the threat of stagflation is becoming more realistic. Coined as a combination of the words “stagnation” and “inflation,” it is an economic backdrop characterized by high inflation, slow economic growth, and in some cases, high unemployment.

In this edition, we examine which asset classes are most exposed to stagflation and which can offer shelter.

Alternatives to Drive Growth in the Next Real Estate Cycle

As the real estate market evolves, alternative sectors are expected to drive significant growth in the coming years. Senior housing, cold storage, industrial assets, and data centers are expected to be particularly popular among investors, with each benefiting from unique factors like demographic changes and technological progress. Senior housing stands out as the sector with the highest projected NOI growth (9.7%) due to an aging U.S. population and the growing demand for retirement communities. Additionally, senior housing properties currently present value-add opportunities, as the average occupancy rate of 85% remains below historical norms due to regulatory challenges and restrictions implemented during the COVID-19 pandemic. As these regulatory pressures ease, there is significant potential for occupancy recovery and rent growth. Properties offering a mix of independent living, assisted living, and memory care units are especially attractive, as they cater to the diverse needs of an aging population and ensure steady revenues. These newer facilities, designed to meet the needs of both residents and their families, often achieve higher occupancy rates and command premium rents compared to older properties, enhancing their investment appeal. Regions with favorable climates, such as the Sunbelt and Mountain areas, are particularly attractive for these investments.

The single-family rental and affordable housing sectors are also gaining traction, as rising homeownership costs and a lack of affordable housing have increased demand for these types of properties. Affordable housing, particularly properties supported by government voucher programs, provides resilient income streams and often generates higher rental yields compared to traditional multifamily assets, making these segments essential in addressing housing shortages in high-growth regions. Data centers and digital infrastructure are becoming critical drivers of NOI growth as well, supported by the rising adoption of cloud services, e-commerce, and advanced computing. Meanwhile, smaller-scale industrial assets and cold storage are thriving due to increased demand for temperature-controlled supply chains and multi-tenant facilities that cater to small businesses. Together, these sectors offer durable demand, scalability, and opportunities to benefit from modern supply chain trends.

While the outlook for these alternative real estate sectors is strong, investment in these spaces does not come without risks. Regulatory challenges, energy consumption concerns for data centers, and liquidity issues in niche sectors like cold storage and affordable housing require careful consideration. That said, the structural trends detailed above should serve as tailwinds for alternative real estate in the years ahead.

New Year, New President…Same Outlook?

From an investor’s perspective, the current environment feels lot like it did twelve months ago: U.S. equity markets returned over 20% the prior year, fixed income is (still) offering attractive yields, and overall portfolio performance was positive for most programs. Nevertheless, nothing lasts forever and sentiment can shift on a dime. It is also likely that some of President Trump’s policies will have an impact on markets, with the specific impact varying by the policy and asset class.

In this edition:

  • U.S. Economy and Policy Expectations
  • Fixed Income: “If you liked it last year, you’ll like it this year”
  • U.S. Equity: Concentration risk still looms
  • Non-U.S. Equities: Positive earnings outlook, policy uncertainty
  • Real Assets: Real estate bottoms, infrastructure demand robust
  • Private Markets: Private equity on the rebound, private credit still compelling